
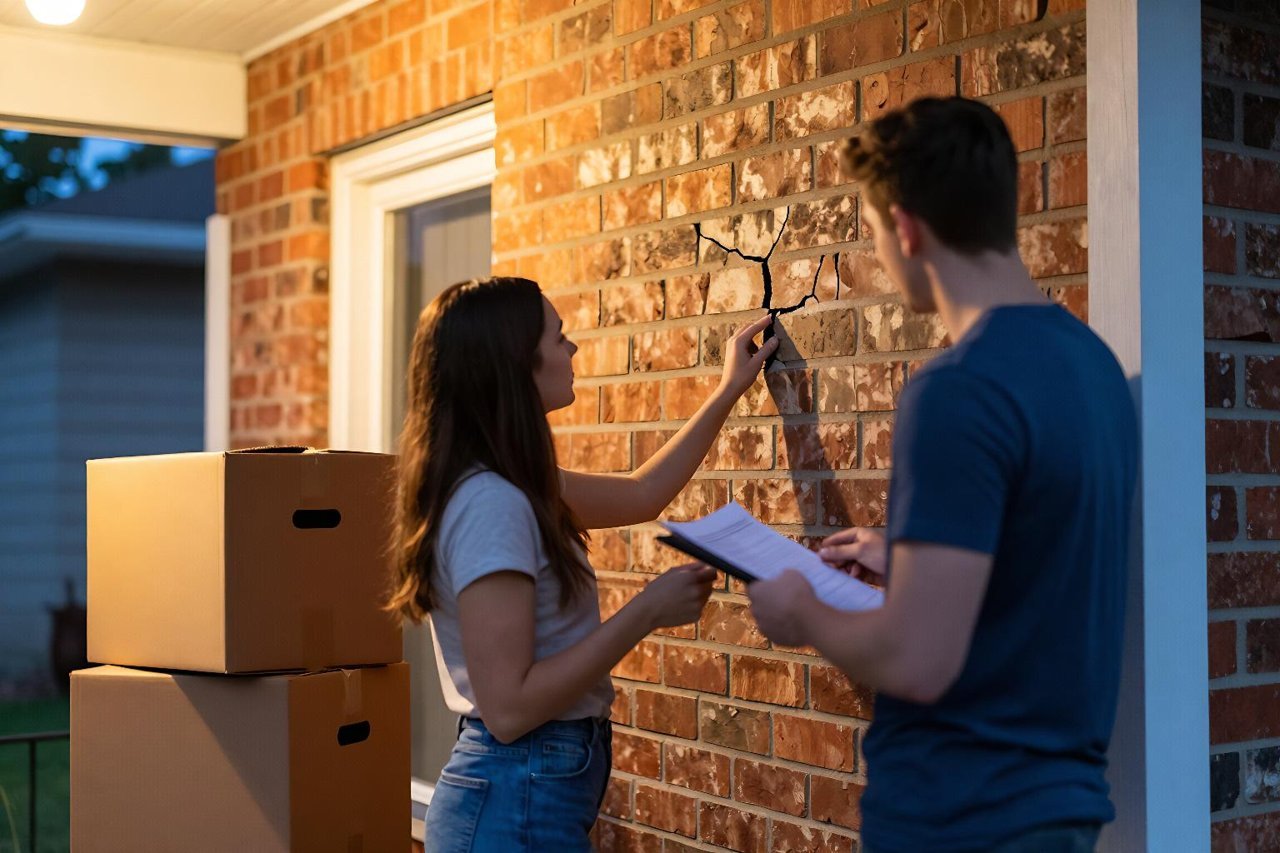
Sarah and her husband found a 1960s ranch with original hardwood floors and a finished basement. It checked every box. To beat three competing offers, they waived the inspection and closed in 21 days. By their first Sunday in the house, the basement carpet was squishy underfoot.
The finished basement sat on a French drain that had failed years earlier. Excavation, new drain tile, and waterproofing ran $14,200, which was their entire furniture budget plus a credit card balance. One signature cost them more than everything else they spent furnishing the house combined.
Most expensive first-time buyer mistakes follow that shape. They look like smart moves under deadline pressure, and the bill arrives months later.
Buying at the top of your approval letter
A lender approving you for $450,000 does not mean a $450,000 house is a good idea. Approval is math run against gross income, and it caps what you can technically repay. It says nothing about whether you can still fund a retirement account, cover daycare, or replace a transmission.
The number that trips people up is the monthly payment. The sticker price is the smallest part of it.
- Principal and interest. The part everyone calculates.
- Property taxes. On a $400,000 home in a 1.8% tax district, that’s $7,200 a year, or $600 a month.
- Homeowners insurance. $1,500 to $3,500 annually in many markets, higher in coastal and hail-prone states.
- PMI. Put down less than 20% and add roughly 0.5% to 1.5% of the loan amount each year.
- HOA dues. $40 a month in a plain subdivision, $600 in a condo tower with a pool and elevators.
- Maintenance. Budget 1% of the home’s value yearly. That’s $4,000 on a $400,000 house, whether or not anything breaks this year.
Stack those together and a $400,000 house can run $3,200 a month before you fix a single thing. Plenty of buyers were approved for that payment and still couldn’t absorb a January furnace replacement.
Mistaking pre-qualification for pre-approval
A pre-qualification letter is a lender’s guess based on numbers you typed into a form. A pre-approval means an underwriter actually reviewed your pay stubs, W-2s, and bank statements. Listing agents can tell the difference in about four seconds, and a pre-qual letter gets sorted to the bottom of the pile in a competitive market.
Even a pre-approval isn’t a promise. Underwriting runs again before closing, against your file as it looks that week.
Skipping the inspection, or hiring the cheapest one
A general home inspection costs $400 to $700 and is the best money in the whole transaction. Skipping it to win a bidding war is how a $14,200 basement becomes your problem instead of a negotiation point.
What general inspectors commonly can’t see is where the real money hides. Specialty inspections are cheap by comparison:
- Sewer scope: $150 to $300. On pre-1980 homes, cracked clay lines and root intrusion are routine.
- Radon test: $150 to $250 in areas with elevated levels.
- Roof and chimney: $200 to $500. Fresh paint hides a lot of rot.
- HVAC age and refrigerant type: a 22-year-old unit running banned refrigerant means full replacement, not repair.
One more consideration. The inspector your agent recommends may be completely honest, but the two of them work together every week. Read reviews on your own and consider hiring someone with no referral relationship to anyone in the deal.
Waiving contingencies to win a bidding war
Contingencies are your exits. Inspection, appraisal, and financing contingencies each give you a way out with your earnest money intact. They feel like weak cards until you need one.
The appraisal gap is the quiet killer. Offer $475,000 on a house that appraises at $455,000 and the lender finances based on the lower number. You cover the $20,000 difference in cash, on top of your down payment and closing costs.
Waive financing and a failed loan means the seller keeps your deposit. On a $450,000 purchase with a 2% deposit, that’s $9,000 gone for a house you never lived in. Waiving inspection on a home with a known foundation crack can be the single most expensive sentence you ever sign.
The costs that appear at the closing table
First-time buyers plan for the down payment and forget everything else. Closing costs run 2% to 5% of the purchase price. On a $400,000 home that’s $8,000 to $20,000 covering lender origination, appraisal, title search and insurance, recording fees, transfer taxes, prepaid taxes and insurance, and escrow setup.
Get a Loan Estimate from at least three lenders and read page two line by line. Origination fees, discount points, and lender credits vary far more between lenders than the advertised interest rate suggests. A rate quoted 0.25% lower with $4,000 in points is not the cheaper loan if you plan to move in five years.
Keep a repair fund separate from the down payment
Water heaters, HVAC systems, and roofs fail on their own schedule. A $7,000 reserve sitting untouched is not wasted money; it’s what keeps the first major repair off a credit card at 24% interest. Buyers who drain every account for the down payment spend their first two years financing emergencies.
Not asking about permits
That gorgeous finished basement, the new deck, the garage conversion. Pull the permit history. Most counties publish it online, and a 10-minute search can change your offer.
Unpermitted work can mean fines, an order to remove the improvement, a denied insurance claim after a fire, and appraisal problems when you eventually sell. It’s also leverage. Ask for the work to be permitted before closing, or ask for a credit large enough to cover bringing it up to code.
Financial moves between offer and closing
Underwriters re-pull your credit before funding. A new car loan at $520 a month can push your debt-to-income ratio past the limit and kill a loan you already celebrated with your family.
- Don’t finance a car, boat, or furniture set.
- Don’t change jobs without telling your loan officer first.
- Don’t co-sign anything for anyone.
- Don’t close old credit cards, even ones you never use.
- Don’t move money between accounts without a documented paper trail.
Treating the final walkthrough as a formality
The walkthrough is your last chance to confirm the seller fixed what they agreed to fix, the appliances are still in the kitchen, and the movers didn’t put a doorknob through the drywall. Bring your signed repair addendum and check each item. Once you sign, those problems are yours, and chasing a seller after closing is a hobby nobody enjoys.
The neighborhood you only saw on a Saturday afternoon
Drive by at 7 a.m. on a weekday, at 6 p.m., and on a Friday night. Traffic patterns, barking dogs, and a train horn three blocks away look very different at those hours than they do on a quiet weekend showing.
Then check three things most buyers never look up: the flood zone, planned development nearby, and how the county reassesses property taxes. That last one surprises people every year. Some states cap how much a tax bill can climb annually until the property sells, then reset to market value. Your first tax bill can land 25% to 35% higher than the seller’s was, and it hits your escrow payment, not just your budget.
Going it alone, or hiring whoever your cousin used
Walk into a showing without representation and the listing agent works for the seller. Having your own buyer’s agent usually costs you nothing extra, because their commission comes out of what the seller already agreed to pay. As a first-timer, that help is worth having on negotiations, paperwork, and timelines.
Just don’t hire on a recommendation alone. Ask how many transactions they closed in the past year, whether they’ve negotiated in your target neighborhoods, and what they charge if you end up buying a for-sale-by-owner property, where the commission arrangement is different.
Run this list before you sign anything
Print it, or keep it on your phone. Every item takes minutes and each one has saved buyers thousands.
- Confirm your payment includes taxes, insurance, PMI, HOA, and 1% maintenance.
- Get a full underwritten pre-approval, not a pre-qual.
- Book a general inspection plus a sewer scope and radon test on any home older than 1980.
- Read every contingency you’re asked to waive, and price the worst case.
- Compare Loan Estimates from three lenders, page two and page three.
- Pull permit history on every improvement the seller mentions.
- Freeze your finances from offer to closing. No new debt, no job changes, no mystery deposits.
- Ask the county what your tax bill will be after the sale, not what the seller pays now.
- Keep $7,000 or more liquid that the down payment never touches.
- Visit the street at three different times of day before you commit.
None of this requires a finance degree. It requires slowing down for about two weeks while everyone around you is telling you to move faster, because the speed is exactly where the thousands disappear.