
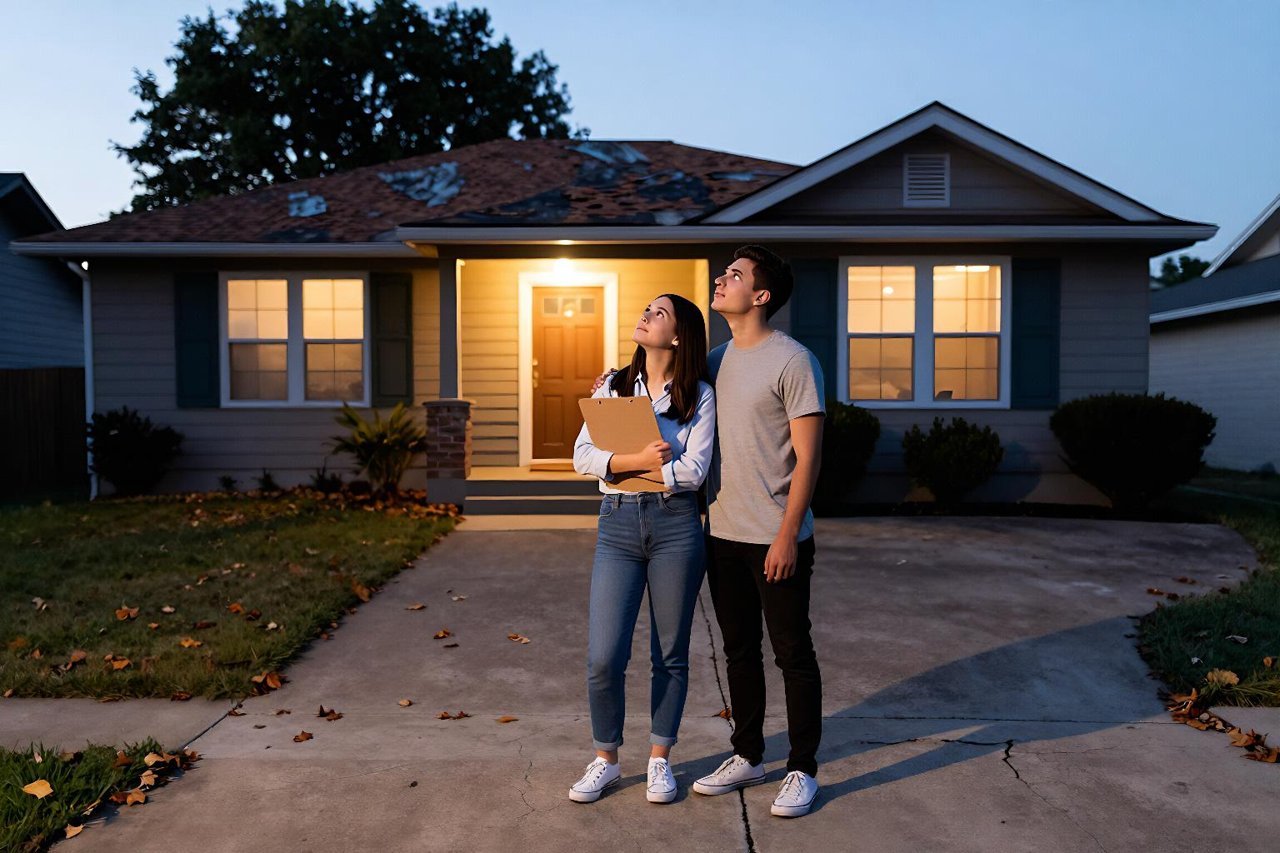
The house had a furnace from 1994, a chimney that leaked into the attic, and a seller who wanted the inspection done in a four-hour window. I almost signed anyway. The kitchen was beautiful, I’d already picked which wall the couch would go on, and my agent kept saying the words “strong offer” in a tone that made me feel like a serious adult.
That near-miss taught me the real shape of first-time home buyer mistakes. They’re rarely dramatic. Nobody gets scammed by a fake listing or hands over cash in a parking lot. Instead, the expensive errors happen in the gaps — a contingency you waved through, a lender you never called back, a monthly payment you never actually added up.
Here are the ones that show up over and over, with the numbers attached.
1. Falling in love before you know your number
Most people tour homes first and figure out financing later. That order is backwards, and it costs you twice — once in wasted weekends, and again in negotiating leverage.
Talk to a lender before your first open house. A pre-approval takes a credit pull, a couple of pay stubs, and usually 24 to 72 hours. It tells you the ceiling you’re working with and flags problems while you still have room to fix them, like a collections account you forgot about or a self-employment income history that needs extra documentation. Showing up to a listing with a verified pre-approval letter is a different conversation than showing up with a guess.
If you want the sequence laid out in the order it actually happens, the first-time home buyer checklist that follows the real timeline is worth reading before you start browsing.
2. Shopping at the top of your pre-approval
A bank approving you for $480,000 does not mean a $480,000 house is affordable. Approval is a debt-to-income calculation, not a lifestyle assessment. It doesn’t know you have a kid in braces, a car that’s due for replacement, or a habit of taking two vacations a year.
Build your own number instead. Take the monthly principal and interest, add property taxes, homeowners insurance, mortgage insurance if you’re putting down less than 20%, and HOA dues. That’s the payment nobody warns you about. Then subtract a few hundred for the things that will break.
3. Draining every account for the down payment
Closing costs typically run 2% to 5% of the loan amount. On a $320,000 mortgage, that’s $6,400 to $16,000 on top of your down payment. Then there’s moving, a washer and dryer, blinds, a lawnmower, and the first repair that comes out of nowhere in week three.
Getting into the house with $400 left in checking is how people end up putting a roof on a credit card. Keep a reserve of at least three months of mortgage payments after closing. If that means a smaller down payment, fine — you’ll pay mortgage insurance, but you won’t be one broken water heater away from a second loan. There are more first-time buyer moves that save real money than most people realize, and most of them are about keeping cash in your pocket rather than stretching to hit a round number.
4. Ignoring down payment assistance you actually qualify for
Thousands of programs exist at the state, county, and city level, plus nonprofit grants and employer-sponsored help. Many are aimed at buyers with incomes well above what people assume — teachers, nurses, and mid-level salaried workers frequently qualify.
The catch is that nobody markets them to you. Loan officers don’t always bring them up, and real estate agents can’t advise on them. You have to ask. A good starting point is the guide to where down payment assistance money actually hides, then call your state housing finance agency directly and ask what you’d be eligible for at your income.
5. Assuming bad credit ends the conversation
Plenty of first-time buyers never start because they assume a 610 credit score disqualifies them. It doesn’t. FHA loans allow scores down to 580 with 3.5% down, and between 500 and 579 with 10% down. Some lenders do manual underwriting for files with no score at all.
The rate will be higher and the lender list shorter, but the door isn’t closed. If your credit is the sticking point, the breakdown of home loans for bad credit and what you’ll realistically qualify for is a more useful read than another six months of guessing.
6. Waiving the inspection to win a bidding war
In a competitive market, waiving the inspection feels like a bold, decisive move. It’s really a $15,000 bet placed on a house you’ve spent 40 minutes inside.
An inspector will look at things you’d never think to check: the age of the water heater, whether the electrical panel is a brand with a known failure record, grading that sends water toward the foundation, a sewer line clogged with roots. You’re not paying for a report. You’re paying for the right to renegotiate or walk.
If you truly have to compete, waive the cosmetic stuff instead. Keep the structural and mechanical inspection, and consider an information-only clause that lets you walk but not ask for repairs.
7. Getting one loan quote and calling it shopping
Rate differences between lenders on the same day, for the same borrower, commonly run 0.25% to 0.5%. On a $350,000, 30-year loan, half a percent is roughly $100 a month, or about $36,000 over the life of the loan.
Get at least three quotes within a two-week window so the credit pulls count as one inquiry. Compare the Loan Estimate line by line, not the headline rate — origination fees, discount points, and lender credits all move the real cost around.
8. Budgeting for the mortgage and forgetting everything else
The payment is the beginning of the cost, not the whole of it. A realistic monthly budget includes:
- Property taxes, which get reassessed after a sale and can jump the year after you buy
- Homeowners insurance, which has climbed sharply in many states and varies enormously by zip code
- HOA dues, plus the special assessments that arrive without warning
- Maintenance, budgeted at roughly 1% of the home’s value per year — $3,800 annually on a $380,000 house
- Utilities, which are usually higher than in a rental, especially for a bigger or older place
Add those up before you make an offer. The sticker price is the least informative number in the entire transaction.
9. Rearranging your finances in the middle of underwriting
Once your file goes to underwriting, your finances are being watched. Lenders re-pull credit and re-verify employment right before closing. A new car loan, a financed furniture set, a job change, or a large unexplained deposit can stall or kill an approval days before you get keys.
Keep it boring. Don’t move money between accounts without a paper trail, don’t co-sign anything for anyone, and tell your loan officer immediately if your employment situation changes.
10. Skimming the HOA documents
HOA packets run 100 pages and read like tax code, which is exactly why people skim them. Read the budget, the reserve study, and the meeting minutes from the last year. Minutes are where you find out about the roofing lawsuit or the $4,000 special assessment that’s about to hit every owner.
Check the rental caps too, even if you never plan to rent. They affect resale value and how easily you can move out later.
The test to run before you sign an offer
Here’s a simple habit that catches most of these mistakes at once. Before you sign anything, write down one number: the true monthly cost of that specific house, including taxes, insurance, mortgage insurance, HOA, and 1% of the price divided by twelve for maintenance.
Then compare it to what you currently pay in rent. If the gap is bigger than the amount you’re saving each month, you don’t have a house yet — you have a plan that needs another year. If the gap fits, you can make an offer with your eyes open instead of your fingers crossed. That single calculation is the difference between a home you can keep and one you’re quietly hoping will appreciate fast enough to bail you out.