
A 2019 double-wide on 1.8 acres, listed at $168,000, sits about twenty minutes outside a mid-size town. A buyer with 3.5% down and a 640 credit score can finance that home with an FHA loan. The same buyer, using the same program, usually cannot finance a nearly identical house sitting on a rented lot in a park ten minutes closer to the grocery store.
The difference is not the house. It is which of FHA’s two manufactured-home programs applies, and whether the land comes with it. That distinction sinks more deals than credit problems, debt ratios, or appraisals ever do.
The Two FHA Programs, and How to Tell Which One You Need
FHA insures two very different loans for factory-built housing. They have separate rulebooks, separate loan limits, and in many cases separate lender lists.
FHA 203(b): the standard mortgage, home and land together
This is the FHA loan most people mean. It works like a normal 30-year mortgage, with 3.5% down and a minimum 580 score for maximum financing. The catch is that the manufactured home has to be permanently affixed to land you own, and it has to be taxed as real property. That last point matters more than it sounds. In many counties a manufactured home carries a title like a vehicle until the owner files an affidavit of affixture with the state, converting it to real estate. No conversion, no 203(b).
FHA Title I: the home-only loan
Title I is FHA’s personal property program. It finances the structure itself, so it can be used when the home sits on land you lease, including a lot in a manufactured home community. Terms typically run up to 20 years on a home-only loan and up to 25 years when a lot is included. The trade-offs are real: interest rates run higher, fewer lenders originate them, and the maximum loan amount is far lower than a county loan limit. Expect a ceiling in the tens of thousands of dollars rather than the hundreds of thousands, and confirm the current cap with the lender because HUD adjusts it periodically.
What the Home Itself Has to Be
Regardless of program, the property has to clear a set of baseline FHA requirements:
- Built after June 15, 1976 to the HUD Code, with the HUD label still attached and the data plate intact inside the home. Pre-1976 mobile homes are ineligible, full stop.
- At least 400 square feet of gross living area and no less than 12 feet wide.
- Permanently affixed to a foundation that meets HUD’s Permanent Foundations Guide for 203(b) loans.
- Connected and working utilities, including water, sewer or septic, and electricity, with no safety hazards or peeling exterior paint.
- Appraised on Form 1004C by an appraiser on HUD’s roster who actually knows manufactured housing.
FHA appraisers are not home inspectors, but they do flag conditions that affect safety and soundness, and they can require repairs before closing. Our breakdown of FHA loan property requirements covers the list of what typically gets called out.
The Foundation Decision Kills More Deals Than Anything Else
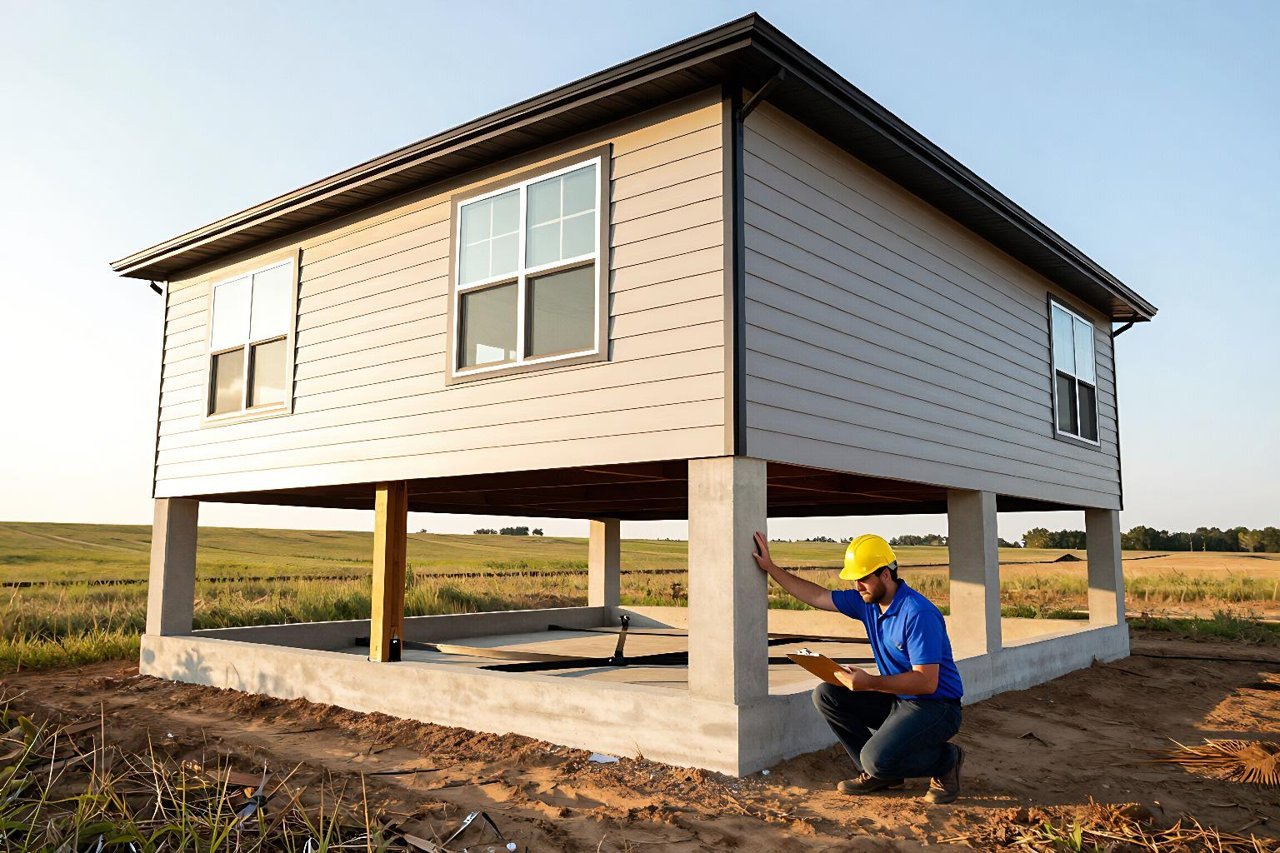
A manufactured home on blocks and a manufactured home on an engineered permanent foundation can look identical from the driveway. Underwriting treats them as different asset classes.
For a 203(b) loan, HUD wants piers poured on footings that sit below the frost line, an anchoring system rated for local wind loads, a vapor barrier over the soil, and proper ventilation. Most lenders also require a certification from a licensed engineer confirming the setup matches the Permanent Foundations Guide. That certification usually runs $500 to $1,500. If the home needs retrofit work, new piers, or an upgraded tie-down system, budget $3,000 to $8,000 or more depending on size and region.
Two more things trip people up here. First, additions and porches built without permits can fail the appraisal even when the main structure is fine. Second, the appraiser has to value the home against site-built comparables, not other manufactured homes, which can pull the number below the contract price in markets with few recent sales.
Loan Limits, Down Payment, and What You’ll Actually Pay
A 203(b) loan follows the same county limit as any other FHA mortgage. For 2025 the floor is $524,225 in low-cost areas, with higher ceilings in expensive markets. Most manufactured homes fall well under that, so the limit rarely binds, but it is worth confirming against your county. The FHA mortgage loan limit guide explains how the cap is set and what happens when a purchase price exceeds it.
Down payment is 3.5% on 203(b). On a $165,000 purchase that is $5,775. You will also pay a 1.75% upfront mortgage insurance premium, which can be rolled into the loan, plus annual premiums that generally land between 0.55% and 0.75% of the balance depending on loan-to-value and term.
Title I works differently. Down payments start near 5%, with the portion of the loan above $25,000 requiring a larger share, and the insurance structure is not the same as standard FHA mortgage insurance. Ask the lender to show you the full payment breakdown in writing, because comparing a Title I quote to a 203(b) quote side by side is not apples to apples.
Credit and Income: Familiar FHA Rules, With a Couple of Twists
The 203(b) side looks like any other FHA file: 580 minimum for 3.5% down, 500 to 579 with 10% down, debt-to-income generally capped around 43% to 50% with compensating factors. Income has to be documented and stable, and gift funds are allowed with a paper trail.
Title I is less standardized. Individual lenders set their own credit floors, and many want 620 or better. Some will not touch a home in a park with fewer than three years remaining on the site lease. That is not a HUD rule so much as a lender overlay, and overlays vary widely, which is why shopping two or three lenders on a home-only deal is worth the effort.
Lot Rent, Insurance, and the Costs Nobody Quotes You
If the home sits on leased land, lot rent is a permanent monthly cost, commonly $400 to $800 and rising. Lenders count it in your debt ratio, and parks can raise it on notice. Insurance on a manufactured home is usually a HO-7 policy rather than a standard HO-3, and premiums run somewhat higher because of wind and age exposure. Expect interest rates roughly a quarter to a half point above site-built financing on the same borrower profile.
Homes on acreage avoid lot rent but bring their own expenses: well and septic maintenance, longer driveways, propane, and sometimes a higher insurance premium for fire protection distance. Buyers comparing the two should run the numbers over ten years, not just at closing. The principles in this guide to an affordable housing mortgage apply directly to that math.
When FHA Isn’t the Right Answer
Plenty of manufactured homes simply do not fit either FHA box. The land is leased with a short-term agreement. The foundation was never engineered. The home has been moved twice and the HUD label is gone. In those cases, a local bank or credit union holding the loan on its own books can be far more flexible than any government program. A portfolio mortgage often approves exactly the property FHA declines, at a higher rate and with a shorter term.
Rural buyers also have options outside FHA. USDA and VA both finance manufactured homes under specific conditions, and local lenders in farm country frequently know the local foundation inspectors by name. This comparison of mortgage types for rural home buyers lays out where each program wins.
What to Line Up Before You Write the Offer
Do the paperwork before the contract, not after. Start with a photo of the HUD label on the tail end of the home and the data plate near the electrical panel. Confirm with the county assessor whether the home is currently taxed as real property or personal property, and if it is personal property, ask what the affidavit of affixture process costs and how long it takes in your state. Request the engineer’s certification from the seller if it exists; if it does not, get a quote so you know the number going in.
Then call the lender and ask one direct question: do you originate FHA 203(b) on manufactured homes, Title I, or both? A loan officer who has to check is not the person to trust with a 45-day closing. Get your pre-approval letter in hand, keep a repair reserve of $5,000 or so for whatever the appraiser flags, and make your offer contingent on the engineer’s report and the appraisal. Sellers of manufactured homes expect those contingencies, and the ones who resist are telling you something useful.